
Key changes:
- The target date for linkage to be operational is 1 January 2028
- EU ETS and UK ETS will operate as separate but linked systems
- Once operational, allowances issued in either the UK or EU ETS can be used for compliance purposes across either scheme.
- This includes compliance with surrender obligations for emissions produced during the 2027 scheme year.
- The UK ETS will align with the EU ETS rules on an ongoing basis
- UK ETS surrender deadline will move to 30 September, meaning for the 2027 UK ETS compliance year the surrender deadline will be 30 September 2028
- Linkage will allow mutual CBAM exemption once fully operational
Until Brexit, the UK participated in the EU ETS. But after Brexit it launched its own UK ETS in 2021.
The UK ETS was closely modelled on the EU ETS, but policy and prices in the two markets have since diverged.
After much speculation for the last 20 months, at the EU–UK summit in Brussels today (20 November), the EU and UK formally approved the agreement to link the two systems with an aim to be operational from 1 January 2028 (a very tight and ambitious Timeframe as we outline below).
This article takes a first look at the draft text and explains what that agreement means, what we still don't know, and what it means for carbon pricing in both the UK and EU, and for CBAM.
What was agreed today
Alongside the summit, two relevant documents were published today: a joint statement and an explainer on ETS linkage.
The documents outline the motivations for linkage and explain linkage at a high level:
Linkage is officially agreed
The EU and UK "welcome the conclusion of the negotiations" on linking their ETSs.
"We aim to apply this agreement from 2028."
The UK government says both sides are working to operationalise the link from 1 January 2028, when "allowances issued in either the UK or EU can be used for compliance across either scheme". The first surrender deadline accepting both is 30 September 2028, for the 2027 compliance year.
Dynamic alignment
The UK will "interpret and apply the same rules at the same time, on an ongoing basis", with an early decision-shaping role on EU rules in development. The two remain "separate but linked" systems, with the UK ETS Authority keeping its decision-making powers.
Cap
The UK cap is subject to an “ambition test”, which sets an upper limit of 62.2m, 59.5m and 57.6m allowances in 2028–30, before an increase for international maritime and outermost-region flights. From 2031, no more than 7.1% of the equivalent EU cap, plus allowances for any later scope additions. The UK can set its cap below these limits.
Market stability
When the link goes live, the UK will remove its Auction Reserve Price, replace its Cost Containment Mechanism with the EU’s Article 29a price-spike mechanism and set up a UK Market Stability Reserve (MSR) of 29.5m allowances, rising to 34.5m by end-2032. It mirrors EU MSR releases from 2028 and intakes from 2031, at 6.7% of EU volumes.
Free allocation
From 2028, the UK aligns with EU benchmark values and the EU phase-out of free allocation for CBAM goods.
CBAM
The EU exemption for UK-origin goods is expected from 1 January 2028, subject to EU legislative procedures. The UK intends to exempt EU, EEA and Swiss-origin goods from UK CBAM a year earlier, from 1 January 2027.
Protections
The UK says it has kept flexibility to set its cap in line with Carbon Budgets, UK-specific transitional free allocation, UK ETS allowances for sustainable aviation fuel, and its own model for integrating greenhouse gas removals.
New Sectors
Where the EU plans to extend the EU ETS to a sector not already within the material scope, it will notify the UK and request that the Partnership Council (established under the TCA) decide to bring that sector within the scope of the linking agreement. The UK is able to expand the UK ETS to wholly new sectors or to new activities or greenhouse gases from existing sectors that are not covered by the EU ETS.
EU ETS 2
(an EU scheme covering emissions from fuel combustion in buildings, road transport and additional sectors) is not in scope of this agreement.
Exit
Either side can temporarily suspend mutual recognition or the CBAM exemption, or terminate the agreement with 18–30 months’ notice.
What we still don't know
The legal agreement and a detailed explainer will be published "in due course". Until then, there a number of open questions.
CBAM
The EU exemption still has to pass through EU legislative procedures, so 1 January 2028 is expected, not guaranteed. The exemptions also cover only goods originating in the UK or EU. Goods from elsewhere crossing the border still face CBAM, with relief for carbon prices already paid.
EU ETS reform
The reform of the EU ETS proposed in July (COM(2026) 616) is still going through the EU legislative process. Once agreed, changes to the linear reduction factor, MSR, free allocation and the CBAM phase-out will pass to the UK through the Joint Committee on ETS Linking.
Other design questions
Treatment of derivatives (reported as the last open issue before the summit), the registry technical standards, secondary market structure and financial regulation detail are still to be set out.
Exit
How allowances held across the two systems would be treated if the link were suspended or terminated.
Expected next steps
The timeline to linkage is packed:
-
Negotiations concluded: 20 November 2026
-
Publication of the legal agreement and a detailed UK explainer: "in due course"
-
Ratification by the European Parliament, Council and UK Parliament: 2027
-
Legislation passed and registry technology updated: 2027
-
Linkage operational (target): 1 January 2028
-
First surrender deadline accepting both UKAs and EUAs: 30 September 2028, for the 2027 compliance year
The 1 Jan 2028 operational target is ambitious. Negotiations concluded within ten months of formally starting in January 2026, but Switzerland's link with the EU took nearly 10 years from the start of negotiations to going live.
Remaining risks
A political agreement for linkage is still not linkage. Significant practical hurdles still remain until linkage is achieved, and in the meantime, there remains an outside chance that the deal could be walked back.
Firstly, linkage is conditional on the UK agreeing a deal on university tuition fees in the next six months. Statements from EU and UK representatives at the summit suggested there is still a gulf in positions, and reaching a deal may not be smooth sailing.
Politics is the main risk - with major elections across Europe and the EU remaining a highly charged topic in the UK.
Timing is also a risk. As discussed above, January 2028 is ambitious and could slip or be delayed, as we've seen with other EU climate policies, like ETS2 and methane regulations, recently.
So what does this mean for…UKA pricing
The expectation of linkage has seen UKAs strongly correlated to EUAs since the idea was first mentioned back in Jan 2025 (see chart below).
However, UKAs have continued to trade at a discount to EUAs. The more confidence the market has on linkage then the narrower the discount. The 2026 average discount is ~£12.70 (-£7 to -£25 range). Today’s announcement of a 2028 start date has largely been priced into the market in recent weeks but as we get further clarity and move closer to certainty on a 1 Jan 2028 start date we will see price convergence.
At the time of writing UKA prices were little changed following the announcement with the discount remaining around -€11.50 / -£9.60 per tCO2e, which is actually wider than the -€10 discount seen last week.
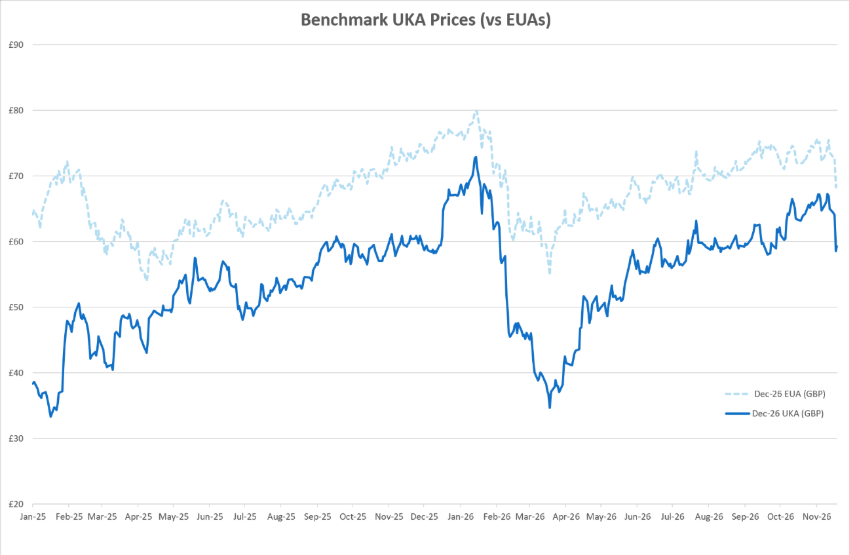
The EUA-UKA spread has moved on sentiment with every linkage headline this year:
- under €10 in January, on early progress
- nearly €30 at the end of March as political nerves hit both markets
- around €13 when the July summit date was confirmed
- wider than €17 after that summit was postponed
- almost €5 tighter in late September, on rumours of a new date
Until a fully operational link, expect the spread to continue price in the political and timing risks discussed above.
EUA pricing
The effect on EUAs should be limited. The UK's 2026 cap is 77.4 million allowances, about 6% of the EU ETS's 1,210 million. Under the reported (unconfirmed) terms, UK issuance would be capped at 7.1% of EU issuance from 2031. Convergence should therefore come mostly from UKAs rising towards EUAs, not EUAs falling to meet them.
CBAM exemptions
The UK government says linkage will exempt around £6.5 billion of UK exports from the EU CBAM. As discussed above, no date is given for CBAM exemption. It is not guaranteed to begin as soon as linkage is operational. Linkage with full price convergence is expected to meet the conditions for mutual exemption, but would no be automatic - both parties would need to update their CBAM regulations. Until then, importers in either direction pay CBAM costs, reduced by any carbon price already paid in the country of origin.
Conclusion
Today's summit was a milestone in post-Brexit EU-UK relations.
But on ETS linkage, we're still left with open questions and risks remain.
Until the 2028 start date and CBAM procedures are confirmed in legislation, expect the EUA–UKA spread to keep moving on headlines and progress.
Given the current discount and ability for EU ETS to potentially use UKAs for compliance with 2027 EU ETS emissions, EU ETS operators should explore purchases of UKA as part of their portfolio
CFP Energy's carbon team is tracking each step. To discuss what linkage means for your EUA and UKA compliance strategy or CBAM exposure, get in touch.
About the author: Polly Thompson
Polly Thompson is the Carbon Policy Lead at CFP Energy, focusing on policy and market analysis across compliance and voluntary carbon markets. She tracks regulatory developments and market trends, helping organisations navigate an evolving carbon landscape.
Related Articles
Share this article


